You pay employees in South Africa in ZAR, and three compliance steps come first: register for PAYE, UIF and, where applicable, SDL; submit your EMP201 and remit the amounts by the 7th of the following month; and issue BCEA-compliant payslips, keeping those records for three years. Everything else in ZAR payroll builds on these three.
TL;DR:
- Register for employees’ tax within 21 business days of becoming an employer, and register with the Compensation Fund within seven days of hiring staff.
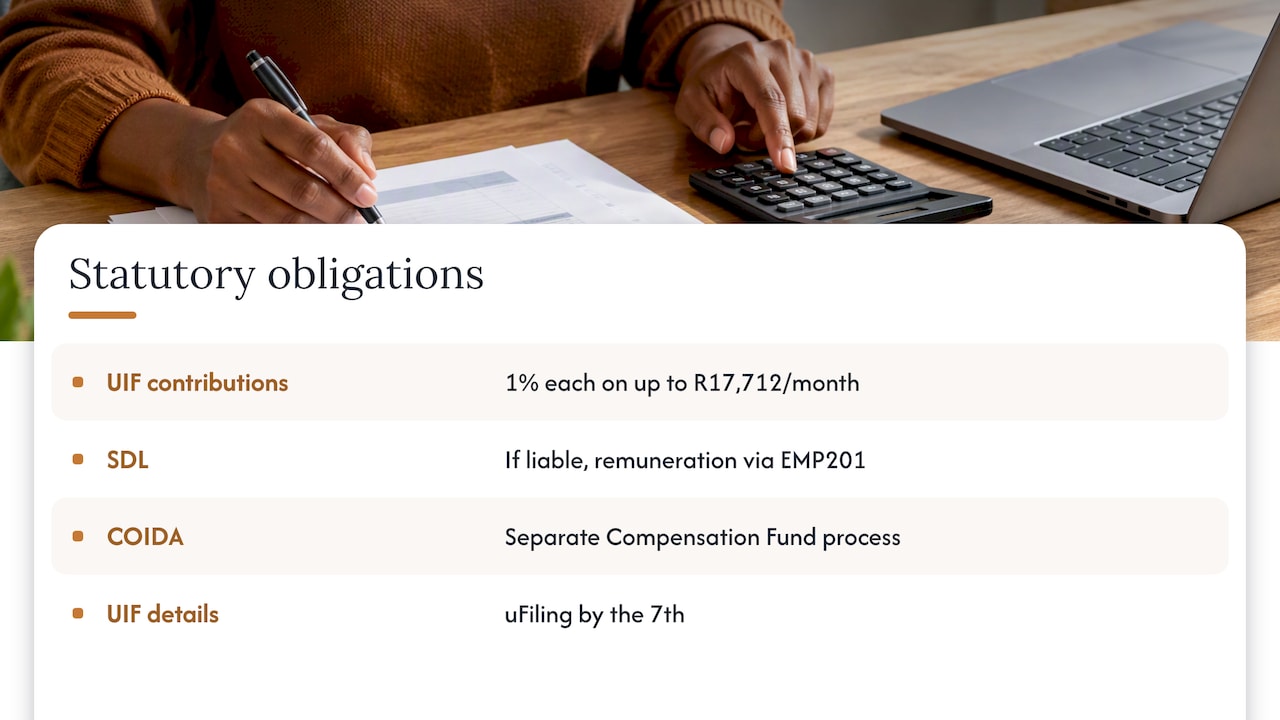
- UIF contributions total 2%, split evenly between employer and employee, but apply only to monthly earnings up to R17,712, capping each share at R177.12.
- Submit the EMP201 first to generate its payment reference number, then pay by credit push; late payment can trigger a 10% penalty plus interest.
- SARS requires interim reconciliation in September and October and annual EMP501 filing in April and May; valid employee tax numbers help prevent certificate rejections.
Table of Contents
- How do you register as an employer and set up ZAR payroll?
- How do you calculate gross pay and statutory deductions?
- What must a payslip contain under the BCEA?
- How does the EMP201 monthly declaration work?
- When do you reconcile and issue IRP5 certificates?
- What should international employers know about paying in ZAR?
- How are statutory benefits and contributions calculated across the year?
- What do skilled roles cost in South Africa compared with the UK and EU?
- How is payroll data protected under POPIA and GDPR?
- How does onboarding through an Employer of Record work?
- Why does a single-country specialist lower payroll risk?
- What do we take off your plate with ZAR payroll?
- FAQ
- Sources
How do you register as an employer and set up ZAR payroll?
Registration comes first, and SARS gives you a fixed window. You must register for employees’ tax within 21 business days after you become an employer. If your payroll makes you liable for SDL, you register for that too and indicate your SETA jurisdiction. Our own payroll tax registration checklist walks through the sequence in more detail.
Work through this list before your first pay run:
- Register with SARS for employees’ tax, and for SDL if it applies to you.
- Register with the Unemployment Insurance Fund and the Compensation Fund where applicable.
- Register each branch separately and report any change of particulars.
- Choose your submission method: eFiling suits employers with 50 or fewer certificates, while e@syFile™ Employer suits larger ones.
- Open a bank account that can pay in ZAR.
- Set up payroll fields for tax number, ID number and UIF number.
- Define how long you keep employee data and who can access it.
Pro Tip: Collect each employee’s valid income tax number at hiring. A missing or invalid number is the most common reason an EMP501 reconciliation gets rejected months later.
For the operational side of running payroll once you are registered, Ready Accounting’s primer on streamlining payroll management is a useful companion.
How do you calculate gross pay and statutory deductions?
Start with gross remuneration: everything you pay an employee for the period before any deduction. From there you work out what to withhold and what you owe as the employer. The SARS employer guide sets out which items count toward employees’ tax and which deductions you may consider.
Four levies sit on top of gross pay:
- PAYE: you deduct employees’ tax from remuneration and remit it to SARS monthly.
- UIF: 2% in total, split 1% from the employee and 1% from you.
- SDL: may be payable depending on your payroll circumstances, and is calculated on remuneration.
- COIDA: you register with the Compensation Fund within seven days of appointing staff and insure workers against occupational injuries and diseases.
UIF has a ceiling that matters for higher earners:
UIF contributions are capped at a monthly earnings ceiling of R17,712, which means the maximum monthly contribution is R177.12 per person. Anything an employee earns above the ceiling is simply left out of the calculation.
Our guide to UIF contributions and the R17,712 cap includes calculation examples if you want to test your payroll system against them.
What must a payslip contain under the BCEA?
Every pay period, you give each employee a written payslip. The BCEA payslip form requires you to keep these records for three years, so build the retention into your payroll system from day one.
A compliant payslip includes:
- Employer and employee details.
- The pay period covered.
- The pay rate and the overtime rate.
- Ordinary hours and overtime hours worked.
- Every deduction, itemized.
Where relevant, show Sunday and public-holiday pay and any averaging of hours so the employee can follow the arithmetic. Clear payslips also make your life easier later, because each figure should reconcile to your monthly EMP201 and to the IRP5 certificate you issue at year end. For a full treatment, see our breakdown of the BCEA payslip rules, and for premium-rate pay see our note on overtime pay and thresholds.
Pro Tip: Print the overtime multiplier next to the hours on the payslip. It settles most pay queries before they reach you.
How does the EMP201 monthly declaration work?
The EMP201 is your monthly declaration of PAYE, UIF and SDL. SARS requires you to submit it, and pay, within seven days after month end. When the 7th falls on a weekend or public holiday, pay on the last business day before it.
The order matters. You submit the declaration first, and SARS generates a payment reference number (PRN) that links your payment to it. That link lets SARS allocate the money correctly across PAYE, SDL, UIF and ETI.
- SARS accepts credit-push payments only; debit-pull has been discontinued.
- Check SARS guidance for the available payment options.
- Employers paying more than R10 million must submit electronically.
- A 10% penalty plus interest can apply to late payments.
- You are personally liable for shortfalls in deducted tax.
| Item | What to remember |
|---|---|
| Deadline | The 7th after month end |
| Sequence | Submit EMP201, then pay with the PRN |
| Payment type | Credit-push only |
| Allocation | Check the EMP201 and SARS guidance for payment allocation |
Our walkthrough of EMP201 deadlines covers the practical filing steps.
When do you reconcile and issue IRP5 certificates?
Payroll is an integrated reporting cycle, and SARS expects you to reconcile twice a year: an interim reconciliation in September and October, and the annual EMP501 in April and May. In each, you reconcile the PAYE, UIF and SDL you declared monthly to the totals on your IRP5 and IT3(a) certificates.
- Plan your submission method early: e@syFile™ Employer for larger employers, eFiling for 50 or fewer certificates.
- Confirm every employee has a valid income tax reference number before you start.
- Fix mismatches between monthly declarations and certificate totals before submitting.
Missing or invalid numbers cause rejections and delays, which is why the data discipline in your setup phase pays off here.
What should international employers know about paying in ZAR?
Paying in ZAR keeps you aligned with local payroll norms and avoids confusion over which currency a contract or payslip refers to. Your remaining job is managing the conversion on your side.
- Schedule currency conversion ahead of your payroll cutoff.
- Use transparent bank or EFT channels, and record when each conversion happened.
- Align your payroll run with EMP201 submission and bank processing times.
- Use the ±1 hour CET overlap to resolve queries with South African banks and advisers within the same working day.
Pro Tip: Set your internal payroll cutoff before the 7th. It leaves room for a rejected submission or a delayed transfer.
How are statutory benefits and contributions calculated across the year?
Statutory contributions follow a simple logic: each one has a rate, a base and, in some cases, a threshold. Getting the base right is most of the work.
UIF uses a capped base. You apply 1% for the employee and 1% for you to monthly remuneration up to R17,712, which equals R212,544 over a year. Beyond that point, extra earnings add nothing. For an employee earning above the ceiling, the UIF base is still R17,712, so each side contributes R177.12.
SDL works differently. If you are liable, it is calculated on remuneration and paid through the same EMP201. Because the threshold is annual, a growing team can cross it mid-year, so track cumulative payroll monthly rather than waiting for year end.
COIDA sits outside the EMP201. It is a separate registration and assessment with the Compensation Fund, and a Letter of Good Standing is issued when your payments are up to date.
UIF returns also have their own channel: registered employers submit employee details through uFiling by the 7th, so confirm which route your registration uses before your first run.
What do skilled roles cost in South Africa compared with the UK and EU?
We do not publish a salary table here, because a range is only useful when it matches a specific role, seniority and city, and we would rather not hand you a number that misleads a budget. What we can say is directional: for skilled roles such as software engineering, finance and operations, South African salaries typically sit well below UK and EU levels, though the difference varies by role, seniority and city.
Two cautions keep that comparison honest. First, salary is not total cost. Add UIF, SDL, COIDA and any benefits to the gross figure before comparing, and the gap narrows slightly even as it stays large. Second, ZAR payroll means your cost in euros, pounds or dollars moves with the exchange rate, so budget with a buffer rather than a single conversion.
If you want a figure for a specific role, our public employment cost calculator turns a gross salary into a full monthly employer cost, and our talent sourcing service can benchmark the market for the profile you are hiring. Because we work in one country only, we see current offers and expectations rather than averages from a global dataset.
How is payroll data protected under POPIA and GDPR?
Payroll data is personal data: names, ID numbers, tax numbers, bank details and salary. For a South African employee of a European company, two regimes can apply at once, POPIA locally and GDPR where your organization or its processors sit in the EU.
In practice, that means a short list of habits:
- Limit access to payroll data to the people who run payroll.
- Document why you hold each data point and how long you keep it.
- Put a written data processing agreement in place with every processor, including payroll providers and banks.
- Know where the data is stored and who can reach it across borders.
Residency is the question European teams ask most. Our data is handled under POPIA and GDPR with EU data residency, which keeps European oversight simple. If you are drafting your own paperwork, our POPIA data processing agreement checklist lists what a processor agreement should cover.
Retention interacts with the BCEA: you must keep payroll records for three years, so deletion policies need to respect that minimum before anything is purged.
How does onboarding through an Employer of Record work?
Hiring through an Employer of Record (EOR) removes the need for you to set up a South African entity or register for PAYE, UIF, SDL and COIDA yourself. The EOR becomes the legal employer, and you direct the day-to-day work.
The onboarding sequence is straightforward:
- Agree the role and terms. You confirm title, salary in ZAR, start date and any benefits.
- Contract signing. A BCEA-compliant employment contract is issued, and with us signed contracts typically follow within 48 hours.
- Payroll setup. Tax number, bank details and statutory registrations are captured so the first ZAR payroll can run.
- Start date. The employee begins, and monthly payslips and EMP201 filings are handled for you.
Full onboarding takes days rather than the weeks a new entity requires. Before you commit to any provider, read our overview of Employer of Record risks, including who legally employs your people. For the wider picture, see our guide to Employer of Record in South Africa.
Why does a single-country specialist lower payroll risk?
Most payroll failures in South Africa are small and local: a missed 7th, a payslip missing an overtime rate, a tax number that never got collected. A provider covering many countries may not focus on those local details every day. A provider that covers one country does, and that is where compliance risk is actually won or lost.
The conventional wisdom says breadth equals safety, because a big platform has seen everything. In my view, that gets it backwards for payroll. Statutory deadlines, certificate cycles and labour rules are specific, and depth beats coverage when a deadline is two days away.
— Roel
What do we take off your plate with ZAR payroll?
We are an Employer of Record for South Africa only. Through a licensed local partner, we handle BCEA-compliant contracts, local ZAR payroll, EMP201 filings, and your UIF, SDL and COIDA obligations, so you do not have to build any of it yourself. Our pricing is flat: from £299 per month per employee, with no setup fees. See our EOR services, or check pricing and onboarding and tell us the role you want to hire.
FAQ
How do you do payroll for employees in South Africa?
Register as an employer, calculate gross pay and statutory deductions, pay in ZAR and issue a payslip. You then submit the EMP201 and pay by the 7th of the following month. See the EMP201 guidance from SARS for the mechanics.
How is PAYE calculated on an employee’s salary?
You work out gross remuneration, consider allowable deductions, and withhold employees’ tax from each payment before remitting it to SARS. The SARS employer guide explains how the calculation is applied for the tax year.
What deadline applies to paying PAYE, UIF and SDL?
You submit the EMP201 and pay within seven days after month end. If the 7th is not a business day, pay on the previous business day.
What is it called when you pay your employees?
It is called payroll. In South Africa that means paying net salary against a compliant payslip and settling the withheld tax and levies with SARS.
Sources
- Form BCEA4 – Pay Slip
- PAYE-GEN-01-G20 – Guide for Employers iro Employees Tax for 2025 – External Guide